

Scam artists are getting bolder, and two of the most common schemes hitting Americans right now have nothing to do with sophisticated hacking. They rely on something far simpler: panic. Recent warnings from law enforcement in Arkansas describe a sharp rise in fraudulent messages claiming to be from the IRS or from toll road operators, with scammers allegedly pressuring victims to pay immediately or hand over sensitive financial information. While the warning came from a department far outside New York, the same playbook is being used against residents of Long Island, Queens, Westchester, and all five boroughs every day.
At DeFreitas & Minsky LLP, CPA, we field calls almost weekly from clients who received an alarming letter, text, or voicemail claiming they owe the IRS thousands of dollars. Most of the time, those messages are fake. Here is what New Yorkers should know about how these scams work, who could be on the hook if you lose money, and what to do next.
What Happened
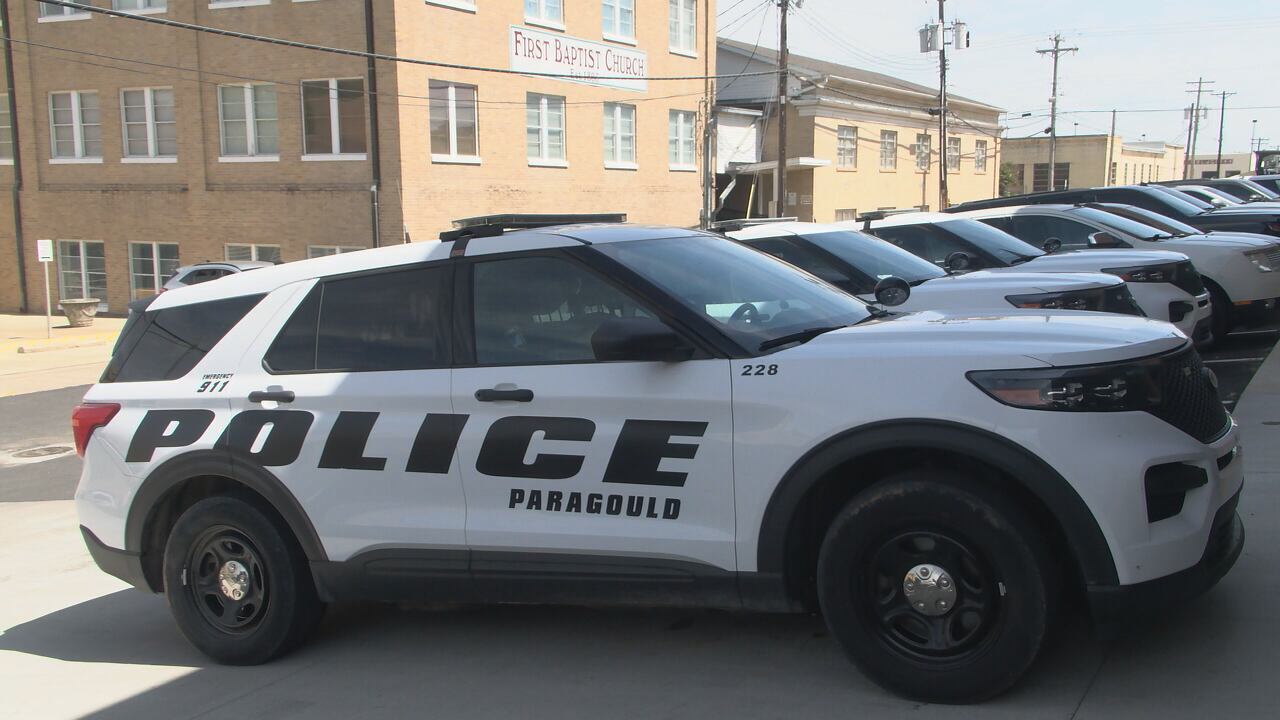
Police in Paragould, Arkansas recently issued a public warning about two scams gaining traction in their community. According to reports, one wave involves messages impersonating the Internal Revenue Service and demanding immediate payment of an alleged tax debt. The second involves text messages claiming the recipient has an unpaid toll balance and must click a link to resolve it.
Law enforcement noted that both schemes follow the same psychological pattern: manufacture urgency, threaten consequences, and push the target to send money or share personal data before they have time to verify anything. In some cases, the scammers allegedly request bank routing numbers, account numbers, or Social Security numbers under the guise of “verifying” the debt. The officer quoted in the report emphasized that no legitimate federal agency contacts taxpayers that way.
While this particular warning came out of Arkansas, identical scams are circulating across New York, often spoofed to look like they come from the IRS, New York State Department of Taxation and Finance, or E-ZPass / Tolls by Mail NY.
Who May Be Liable
If you have lost money or had your identity stolen through one of these schemes, several parties could potentially be liable, depending on the facts:
- The individual scammers and their networks. The people running these operations could be liable under federal wire fraud, identity theft, and tax fraud statutes. The challenge is that many operate overseas and are difficult to locate.
- Payment processors and money transmitters. In limited circumstances, gift card retailers, wire services, or cryptocurrency exchanges may be liable if they failed to follow required anti-fraud protocols.
- Financial institutions. If your bank ignored clear red flags or failed to reverse unauthorized transactions under Regulation E, it may bear some responsibility.
- Telecom carriers and platforms. Carriers that allegedly failed to block known spoofed numbers, or platforms that ignored repeated abuse reports, could face regulatory exposure, though private recovery is usually limited.
We always use the words “may be liable” because liability is fact-specific. Every case has to be evaluated on its own circumstances.
Legal Theories That May Apply
Several legal theories could come into play for a New York victim:
- Federal wire fraud and mail fraud. These statutes target schemes that use electronic communications or the postal system to defraud, and they form the backbone of most IRS-impersonation prosecutions.
- Identity theft under federal and New York law. New York Penal Law §§190.78–190.80 criminalize identity theft, and victims may also have civil remedies.
- Common law fraud and conversion. Where money was taken under false pretenses, civil claims for fraud and conversion may exist against any recoverable defendant.
- Negligence by a financial institution. If a bank disregarded its own fraud-monitoring protocols, a negligence theory could apply.
- Violations of the Electronic Fund Transfer Act (Regulation E). Consumers have specific rights when unauthorized electronic transfers hit their accounts, and banks that fail to honor those rights could be liable.
- Telephone Consumer Protection Act (TCPA) claims. Where robocalls or unsolicited texts violate federal communication rules, statutory damages may be available.
Damages Victims May Recover
What you may be able to recover depends heavily on how much was lost, how quickly the fraud was reported, and which defendants are reachable. Potential categories include:
- Direct financial losses – the actual dollars wired, loaded onto gift cards, or transferred.
- Costs of restoring credit and identity – credit monitoring, fees to freeze and unfreeze credit, notary and certified mail expenses.
- Tax preparation and amendment costs – if a fraudulent return was filed in your name, you may incur substantial CPA fees to unwind it.
- Emotional distress damages – available in some intentional tort claims, though typically harder to recover.
- Statutory damages – available under certain federal consumer protection statutes regardless of actual loss.
- Punitive damages – possible where intentional fraud is proven against a reachable defendant.
New York’s general statute of limitations for fraud is six years from the act or two years from discovery, whichever is later, but other claims (such as Regulation E disputes) have much shorter windows — sometimes as little as 60 days.
Evidence That Strengthens a Case
If you suspect you’ve been targeted or victimized, preserving evidence is critical. Helpful documentation includes:
- Screenshots of every text, email, or pop-up, including phone numbers, sender addresses, and URLs.
- Voicemails saved in their original format, plus call logs showing dates and times.
- Copies of any letters received in the mail, including envelopes and postmarks.
- Bank and credit card statements showing the disputed transactions.
- Receipts for gift cards, wire transfers, or cryptocurrency purchases.
- Records of every call you made to your bank, the IRS, or law enforcement, including reference numbers.
- IRS Identity Theft Affidavit (Form 14039), FTC IdentityTheft.gov report, and local police report numbers.
In a tax-fraud context, IRS transcripts (which we can pull for clients) often reveal whether a fraudulent return has been filed under your Social Security number — a key piece of evidence.
What to Do Next
If you receive a suspicious communication claiming to be from the IRS or a toll agency, slow down. The IRS does not initiate contact by text, email, or social media, and it does not demand immediate payment by gift card, wire, or cryptocurrency. New York’s toll authorities will not threaten arrest for an unpaid $6.99 toll.
Practical steps:
- Do not click links or call back numbers from the suspicious message.
- If you already paid or shared information, contact your bank immediately to attempt a reversal or account freeze.
- File reports with the FTC at IdentityTheft.gov, the Treasury Inspector General for Tax Administration (TIGTA), and your local police.
- Place a fraud alert or credit freeze with all three credit bureaus.
- If a tax return was involved, file IRS Form 14039 and request an Identity Protection PIN.
- Avoid making recorded statements to anyone — including callers claiming to be “fraud recovery” services, which are often a second layer of the same scam.
If you or a loved one has lost money, had a fraudulent tax return filed in your name, or simply doesn’t know whether a notice you received is real, the team at DeFreitas & Minsky LLP, CPA can help you verify the document, communicate with the IRS on your behalf, and chart the right next step. Call (516) 689-1515 or visit https://dmaccountingfirm.com. Talk to DeFreitas & Minsky for 70+ years of trusted CPA guidance – free consultation.
Frequently Asked Questions
How can I tell if an IRS notice I received is real?
Legitimate IRS notices generally arrive by U.S. mail, reference a specific tax year and form, and include a notice number (such as CP2000 or LT11) in the top corner. The IRS does not initiate contact by text, email, or social media. If you are unsure, a CPA can pull your IRS account transcripts to confirm whether the balance is real.
Can I sue the scammer who took my money?
In theory, yes — fraud and conversion claims may exist. In practice, most scammers operate overseas or through shell accounts, making recovery difficult. A more practical path is often pursuing your bank, payment processor, or credit card issuer for chargeback or Regulation E relief.
What if I already gave them my Social Security number?
Act fast. File an identity theft report at IdentityTheft.gov, submit IRS Form 14039, request an IRS Identity Protection PIN, and place a credit freeze with Equifax, Experian, and TransUnion. The sooner you lock things down, the harder it is for the scammer to file a fraudulent return or open new accounts.
What if a fake tax return was filed in my name?
This is sometimes the first sign of fraud — your e-filed return is rejected because one was already filed. You’ll need to file a paper return with Form 14039 attached. The IRS Identity Theft Victim Assistance unit will investigate, but resolution can take months, so working with a CPA is strongly recommended.
How long do I have to dispute unauthorized charges to my bank?
Under federal Regulation E, you generally have 60 days from the statement date to dispute unauthorized electronic transfers. Waiting longer can dramatically reduce your protection. Credit card chargebacks under Regulation Z often allow 60 days from the statement as well.
Are toll text scams really illegal, or just annoying?
They are illegal under federal wire fraud statutes and, depending on the content, may also violate the TCPA and state consumer protection laws. Even if you didn’t lose money, reporting the message helps regulators build cases. Forward suspicious texts to 7726 (SPAM) and report them to the FTC.
Can the IRS arrest me if I don’t pay immediately?
No. The IRS does not send police to your door over a phone call, and it does not demand payment by gift card, wire, or cryptocurrency. Any caller threatening immediate arrest for unpaid taxes is almost certainly running a scam.
Should I talk to the caller to gather information for police?
No. Engaging with scammers tends to escalate the contact and can put you at greater risk. Hang up, save any voicemails, document the number, and report it to the FTC, TIGTA, and your local police department.
Original reporting: kait8.com.


